All Categories
Featured

Predicting the Next GCC Corporate Environment
Table of Contents
To reverse a years of deteriorating overall element productivity, local labour market policy is shifting from basic task creation to managing active labor force transitions. Governments and companies are scaling short, modular training programs and micro-credentials in information analytics and digital operations to equip employees for emerging roles. Workplace-based learning and apprenticeship-style paths are becoming more common as companies incorporate AI tools into day-to-day workflows.
With oil rates anticipated to average $55-60 per barrel in 2026, local governments are intensifying their concentrate on expense discipline and private capital mobilisation. Fiscal policy is pivoting toward the monetisation of state-owned possessions in logistics, energies, and desalination to redirect funds towards higher-impact investments. While loaning by means of sukuk and sustainability-linked bonds is anticipated to increase to fund strategic deficits, the focus remains on enhancing non-oil profits structures.
PwC Middle East economic policy and method partner Jing Teow said: "Having already mobilised capital and policy at scale, GCC federal governments are now focused on shipment. In 2026, the priority is strengthening financial resilience through more secure trade and financial investment relationships, reliable AI implementation, managed labor force shifts and disciplined fiscal policy in a more tough and fragmented worldwide environment.".
Saudi Arabia and UAE are poised to lead the Gulf region's financial expansion in 2026, supported by strong private-sector efficiency, resistant domestic need and renewed investment momentum, according to the current ICAEW Economic Insight Q4 2025 report, produced by Oxford Economics. The GCC is anticipated to outperform most international areas peers next year, with regional GDP projection to grow by 4.4%. Throughout the GCC, non-energy activity is predicted to broaden by 4.1% in 2026, driven by strong labour markets, improving credit conditions and increasing investment in innovation and AI-related facilities.
Oil earnings will be under pressure in the first half of 2026, production is anticipated to increase again in the second half of 2026, supporting the region's medium-term outlook, it specified. Saudi Arabia will remain a significant contributor to GCC momentum, with GDP projection to grow 4.3% in 2026.
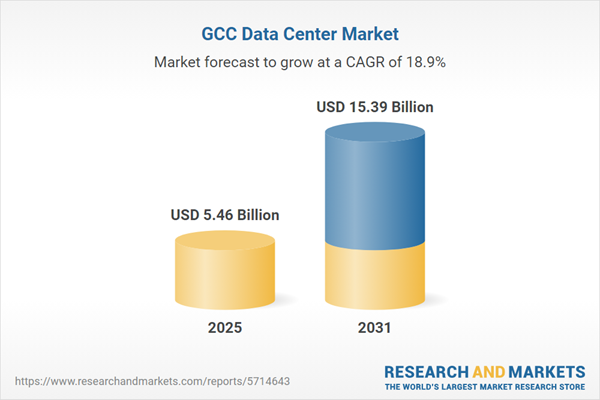
Accelerating Regional Corporate Growth through Strategy
Growth will be supported by industrial expansion and policy reforms, including alleviated foreign ownership guidelines that aim to stimulate more investment. The fiscal deficit is forecasted to widen to 5.6% of GDP next year amidst softer oil rates, while the current five-year rent freeze in Riyadh aims to reduce inflationary pressures, though it may constrain future housing supply.
Strong domestic fundamentalsThe UAE is also placed for another strong year of efficiency, with GDP forecast to increase 5.6% in 2026 as non-oil sectors continue to expand. Tourist, trade and financial services stay crucial development motorists, supported by population growth and sustained domestic demand. Dubai's economy grew 4.4% in the first half of 2025, reflecting broad-based non-oil strength.
Oil production is expected to pick up again in the 2nd half of 2026, matching continuous financial investment in facilities, innovation and global trade partnerships. Hanadi Khalife, the Head of Middle East, ICAEW, said: "This quarter's outlook enhances how far the GCC has can be found in building varied, resilient and globally competitive economies.
Why Data Shapes Regional Corporate VisionScott Livermore, ICAEW Economic Advisor, and Chief Economist and Handling Director, Oxford Economics Middle East, said: "Saudi Arabia and the UAE are entering 2026 with strong structures. Saudi non-oil activity is getting pace, supported by robust need and rising investment, even as financial pressures increase.""The UAE continues to benefit from solid domestic fundamentals, a sharp uplift in federal government costs and continual diversification efforts.
Why Data Shapes Regional Corporate VisionCan Market Analytics Drive Middle East Corporate Success?
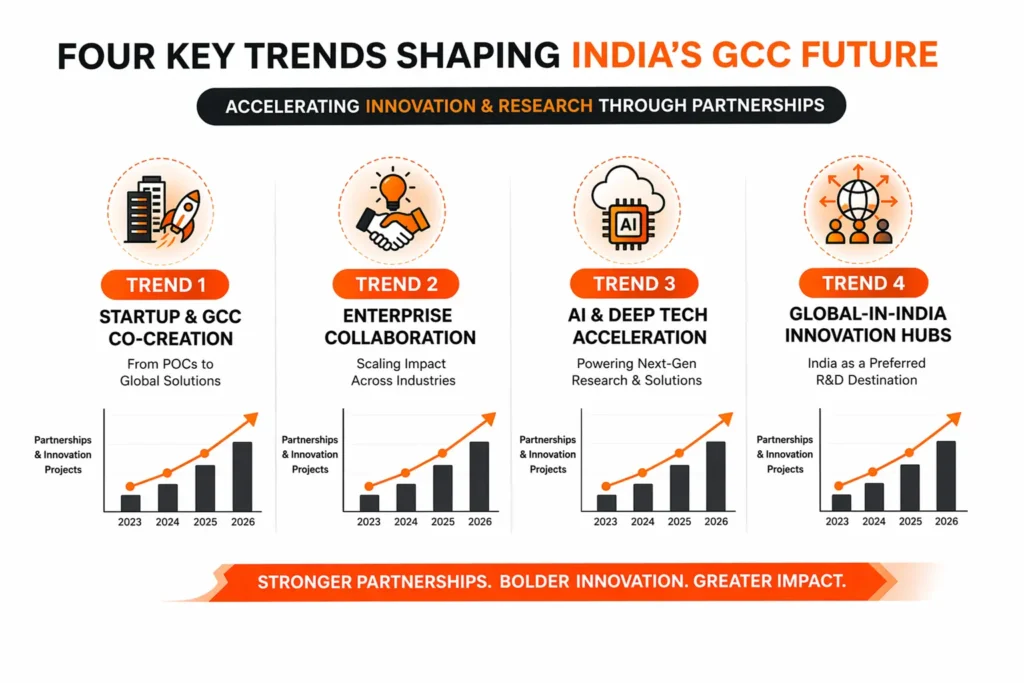
What distinguishes 2026 from preceding years is not merely the acceleration of technological change, though that velocity is genuine, but rather an essential shift in how enterprises develop of their GCCs' function. The is anticipated to grow to four hundred thirteen billion dollars by 2040, however this development masks a more profound transformation.
Rather, they ask whether these centers drive innovation, own profit-and-loss obligation, and contribute to competitive distinction. In 2026, the most effective GCCs will act like internal start-ups, nimble, cross-functional, insight-driven, and deeply lined up with global company outcomes. This shift from execution to ownership represents maybe the single most significant strategic recalibration in the GCC model's evolution.
Today, we're assembling more than 3000 conferences in between investors and 119 Gulf-listed business with a combined value of $2.4 trillion at the HSBC GCC Exchanges Conference 2026, in London. We're combining investors, companies, exchanges, and policymakers to discuss what is altering in the region, and what comes next, including the expansion and ongoing advancement of the Gulf's capital markets, and the region's growing function in global networks of capital and trade.

Latest Posts
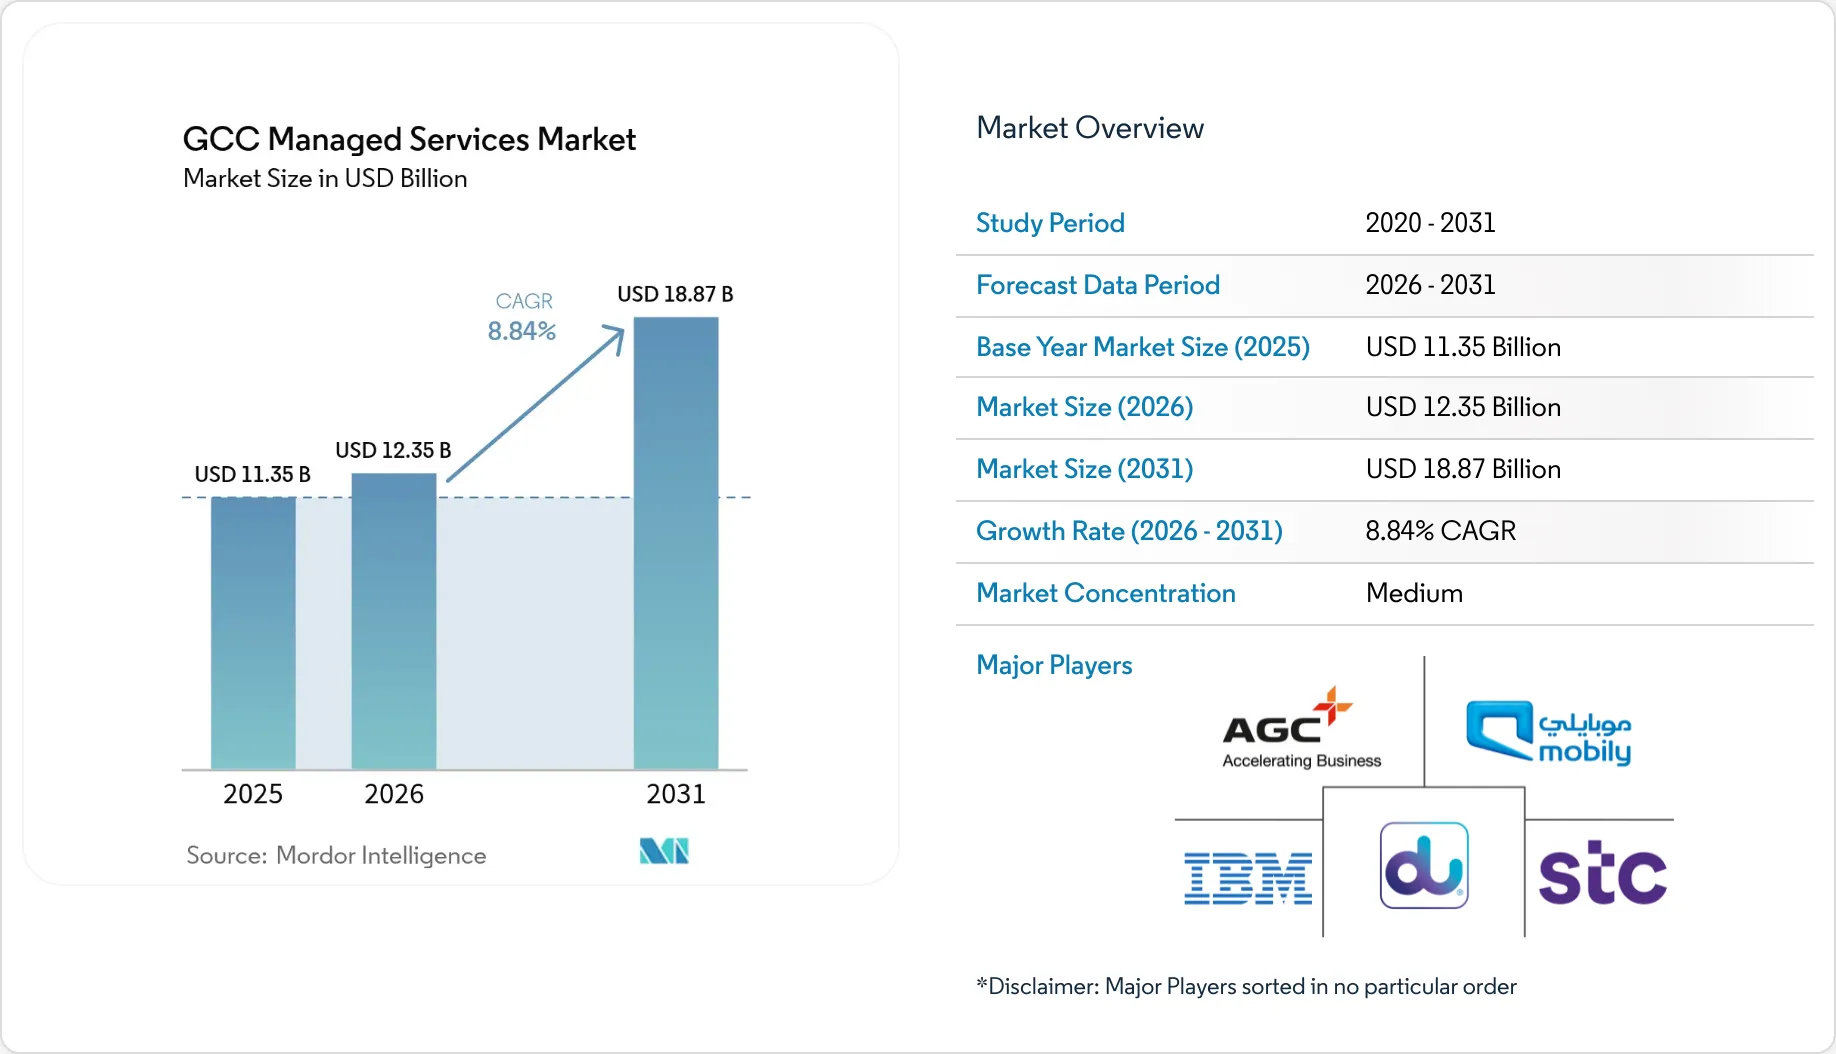
The Benefits of Industrial Excellence for Dubai
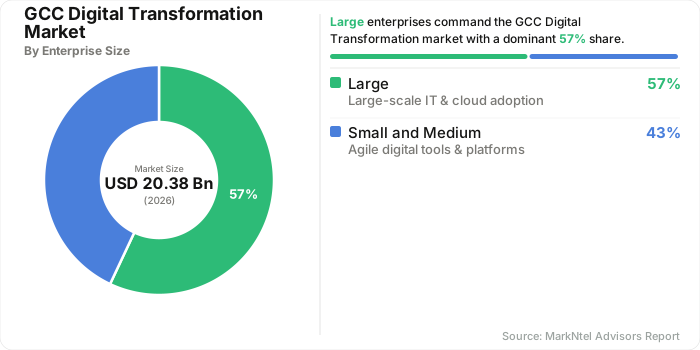
Driving Regional Industrial Growth through Strategic Excellence

Middle East News: Strategic Corporate Trends for 2026